What Does a Bank Need to Finance a Barndominium?
Construction lending for barndominiums is achievable — but it requires a specific document package most buyers don't know about.
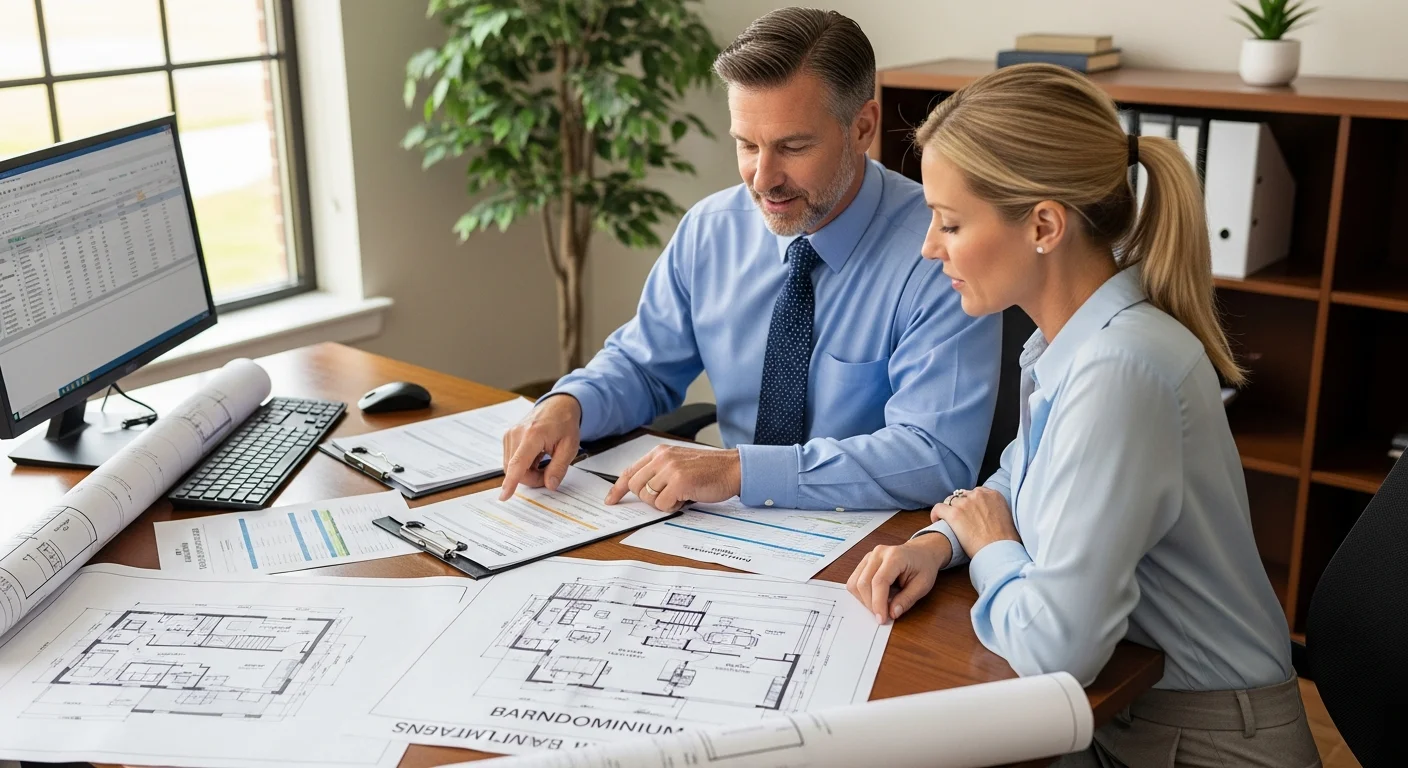
“The lender doesn't need a perfect barndominium — they need a complete file. Ninety percent of barndominium financing problems I've seen are document problems, not qualification problems. The buyer qualified; they just didn't have the file organized.”
John Piazza Norton — Founder, DreamStart Building Company
Bottom Line Upfront
A barndominium construction loan requires eight key documents: engineered drawings, signed builder's contract, builder's license and insurance, itemized cost breakdown, land deed, residential classification evidence, personal financial package, and (when available) HERS documentation. SIP Homestead Shells built to IRC code qualify for conventional, FHA, USDA, and VA financing.
The "banks won't finance barndominiums" myth persists because some banks won't finance some barndominiums — the ones built to agricultural or commercial specs, without residential engineering, by contractors with no documentation package. A properly built SIP Homestead Shell with a complete lender file is a standard construction loan.
The Complete Lender Document Checklist
Engineered drawings with PE stamp
Site-specific engineering from a licensed Missouri professional engineer. Generic plans are not acceptable. Your builder should provide these as part of the project.
Signed builder's contract with draw schedule
The bank needs to see the full contract, including the payment draw schedule tied to milestones. This tells them how construction funds will be released.
Builder's license and certificate of insurance
Your builder's general liability insurance certificate and proof of contractor registration. Lenders won't fund a project with an uninsured contractor.
Itemized cost breakdown
A line-item budget showing all project costs: shell, foundation, site work, utilities, interior finish. Lenders use this to establish the loan amount and draw schedule.
Land deed or purchase contract
Proof that you own the land or are actively under contract. The land is typically pledged as part of the construction loan collateral.
Residential classification evidence
Documentation that the structure will be built to IRC residential code — not commercial or agricultural. For SIP shells, this includes the engineering package that references IRC compliance.
Personal financial package
Standard mortgage documentation: 2 years of tax returns, W-2s or 1099s, 2–3 months of bank statements, and a credit authorization.
Builder's HERS rating documentation (when available)
Some lenders, particularly those offering energy-efficient mortgages, want HERS documentation. A SIP shell scoring HERS 40–55 can qualify for preferential terms with some programs.
Loan Types That Work for Barndominium Builds
Conventional construction-to-permanent
Available from most banks and credit unions. Down payment typically 10–20%. Converts to permanent mortgage after CO is issued.
Ideal for: Best for buyers with strong credit and 10–20% equity in land + down payment
USDA Rural Development
Zero down payment option for eligible rural areas and income-qualifying buyers. Available in most of rural Missouri.
Ideal for: Best for first-time buyers in rural areas with moderate income
VA Construction Loan
For veterans who meet occupancy requirements. Zero down, no PMI. Requires VA-approved builder and appraisal.
Ideal for: Best for veterans building their primary residence
Farm Credit Services
Agricultural lenders who often understand rural construction better than traditional banks. Flexible underwriting for rural properties.
Ideal for: Best for buyers with agricultural land or farm income
Frequently Asked Questions
What documentation does a bank need for a barndominium construction loan?
For a barndominium construction loan, banks typically require: engineered drawings stamped by a licensed PE, a signed builder's contract with payment draw schedule, builder's license and certificate of insurance, cost breakdown by line item, land deed or purchase contract, evidence that the structure will be classified as residential (IRC code compliance documentation helps here), and a standard personal financial package (tax returns, W-2s, bank statements).
Do SIP barndominium builds qualify for conventional loans?
Yes. SIP Homestead Shells built to IRC residential code qualify for conventional construction-to-permanent financing, FHA, USDA Rural Development, and VA loans (for veterans who meet occupancy requirements). The key is documentation that shows the structure is classified and built as a residential dwelling, not a commercial or agricultural building.
What is a construction-to-permanent loan and how does it work for barndominiums?
A construction-to-permanent loan has two phases: during construction, you draw funds on a schedule tied to build milestones and pay interest only on drawn amounts. After construction is complete and the certificate of occupancy is issued, the loan converts to a standard permanent mortgage. This is the most common financing structure for barndominium builds.
Can I get a USDA loan for a barndominium in Missouri?
USDA Rural Development loans are available for qualifying barndominiums in eligible rural areas — which covers most of rural Missouri. The property must be the primary residence, the applicant must meet income limits, and the structure must be classified as residential. SIP Homestead Shells built to IRC residential code generally meet USDA requirements.
Related Reading
About DreamStart
We used to build barndominiums and homestead shells with our own hands — and that experience is exactly what taught us where the real value lies: in getting the design right, planning the build carefully, and working successfully alongside local builders hired by owners. That hands-on experience helps us prepare clearer planning and handoff materials, but it does not make DreamStart the party choosing your contractor. DreamStart now operates as a pre-construction planner and design advisor — not a builder, general contractor, installer, or construction manager. We produce your custom drawings and documentation, coordinate engineering only when your county or lender requires it, and guide site-readiness and logistics. DreamStart designs the plans, organizes the steps, and gets the EPS panels ordered and delivered at the quoted package pricing for your local builder to set. We do not self-perform or include general-contractor labor, excavation, foundations, shell erection, utilities, or finish-out — that work is performed by your local builder and trades you retain, contract, and pay directly. We help you find a general contractor and hold a three-way interview, then hand off a clear written plan. DreamStart does not perform or manage field construction; each owner independently selects, contracts, pays and schedules their contractors. Verify the GC's qualifications, insurance, permit requirements, and lender requirements with the appropriate local authorities and your lender.
Take the Next Step
Ready to Price Your Homestead Shell?
DreamStart designs the plans, organizes the steps, and gets the EPS panels ordered and delivered at the quoted package pricing for the local builder you hire to set. Your GC handles construction. Get your custom estimate free, no obligation.