Your Bank Said No.
Here's What to Do Next.
Most barndominium and homestead shell loan denials aren't a credit problem — they're a documentation problem. The banks saying "no" don't know how to handle SIP construction. We do.
You're Not Alone
"We are having multiple banks tell us they cannot bc it's considered an accessory structure with living quarters. Appraisal went thru then they backed out saying there's not enough collateral and it's too risky bc there aren't enough comps. Basically barndos are being built not sold so there's no comps. Also that if we wanted to sell it would be hard for a person to find a bank to supply a mortgage on a barndo. Has anyone had this issue! We are being told there's nothing they can do!"
The banks aren't wrong — they just don't know who to call. DreamStart does.
Why Banks Say No
Three specific problems cause almost every barndominium denial — and each has a documented fix.
"Accessory Structure" Classification
Lenders flag combined living/utility structures as outbuildings, not primary residences. Their underwriting system wasn't built for this.
Correct the permit language to 'single family residential dwelling.' Provide primary dwelling designation and a cost-approach appraisal.
No Comparable Sales
Appraisers need comps. In rural areas, there may be fewer than 5 barndominium sales on record — so the appraiser can't validate value.
Use cost-approach appraisal instead of sales comparison. A HERS energy rating of 40–55 adds documented value that appraisers can use.
SIP Construction Unfamiliarity
Underwriters trained on stick-frame construction may flag SIP panels as 'non-standard' — even though they're ICC-certified engineered components.
Builder provides a lender education package: EPS Authorized Dealer cert, engineering specs, energy performance data, and a direct conversation with the underwriter.
Our Recommended Lender
DreamStart works directly with Chris Miller — a nationwide lender who specifically understands SIP construction and barndominium financing.
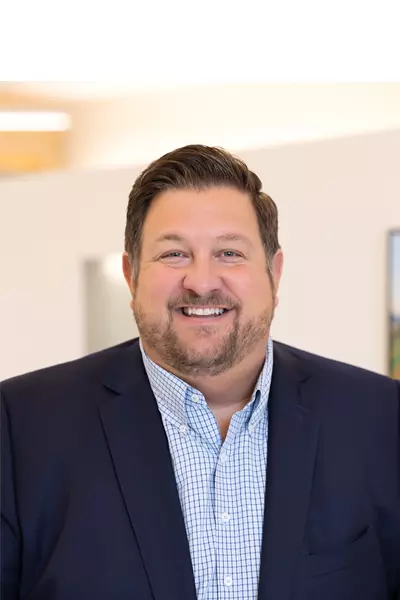
Chris Miller
Chris has been in the mortgage business for almost 20 years and is the #1 residential and construction loan producer at First Federal Bank of Kansas City. He's navigated the "accessory structure" classification problem, no-comp appraisals, and SIP construction unfamiliarity with underwriters many times — and he works directly with our team when questions come up.
You can contact Chris directly, or fill out the form below and we'll make a personal introduction with your project details already shared.
How the Introduction Works
We don't hand you a phone number and wish you luck. We brief Chris on your situation first, so your first call is productive.
Step 1: Tell Us Your Situation
Fill out the form below. We want to know which lenders you've already tried, what state you're building in, and what the denial reason was (if you got one).
Step 2: John Reviews Your Profile
John Norton reviews your submission directly — your build state, location, acreage, loan type eligibility, and any prior denials. Most responses within 1 business day.
Step 3: We Introduce You to Chris Miller
John connects you to Chris Miller, our recommended nationwide lender. We send Chris our documentation package on your project before your first conversation, so he's already up to speed.
Step 4: We Support the Loan Through Closing
If Chris's underwriting team has questions about SIP construction, our team speaks with them directly. We provide engineered drawings, EPS certification, energy specs, and timeline documentation.
Get Matched with a Lender
Tell us your situation. We'll respond within 1 business day.
Common Questions
Can I get a loan for a barndominium after being denied?
Yes. Most denials happen because the lender lacks experience with barndominium or SIP construction — not because you don't qualify. USDA Rural Development, Farm Credit Services, and community banks with rural lending programs are more likely to approve barndominium construction loans. DreamStart connects buyers with lenders who have approved SIP construction projects before.
What does 'accessory structure with living quarters' mean to a lender?
This classification treats your home like a detached garage or barn with a loft — not a primary residence. It triggers denial because the lender's underwriting guidelines are built for conventional homes. The fix is documentation: a primary dwelling permit, a cost-approach appraisal, EPS Authorized Dealer certification, and a HERS energy rating. DreamStart provides the first three; we recommend a third-party HERS rater for the fourth.
What types of loans work for barndominium shells?
USDA Rural Development Section 502 loans are often the best fit for rural land builds — no down payment required for eligible buyers. VA loans work for veterans meeting occupancy requirements. Construction-to-permanent loans from community banks and Farm Credit branches are the most flexible. FHA loans can work when the property is appraised correctly. DreamStart has worked with buyers using all four types.
Does DreamStart help with lender communication directly?
Yes. When a lender has questions about SIP construction or our build process, our team speaks directly with the underwriter. We provide an engineering package (site-specific PE-stamped drawings), EPS Authorized Dealer certification, energy performance specifications, and construction timeline documentation. Many approvals happen after this conversation.